
Disability Insurance
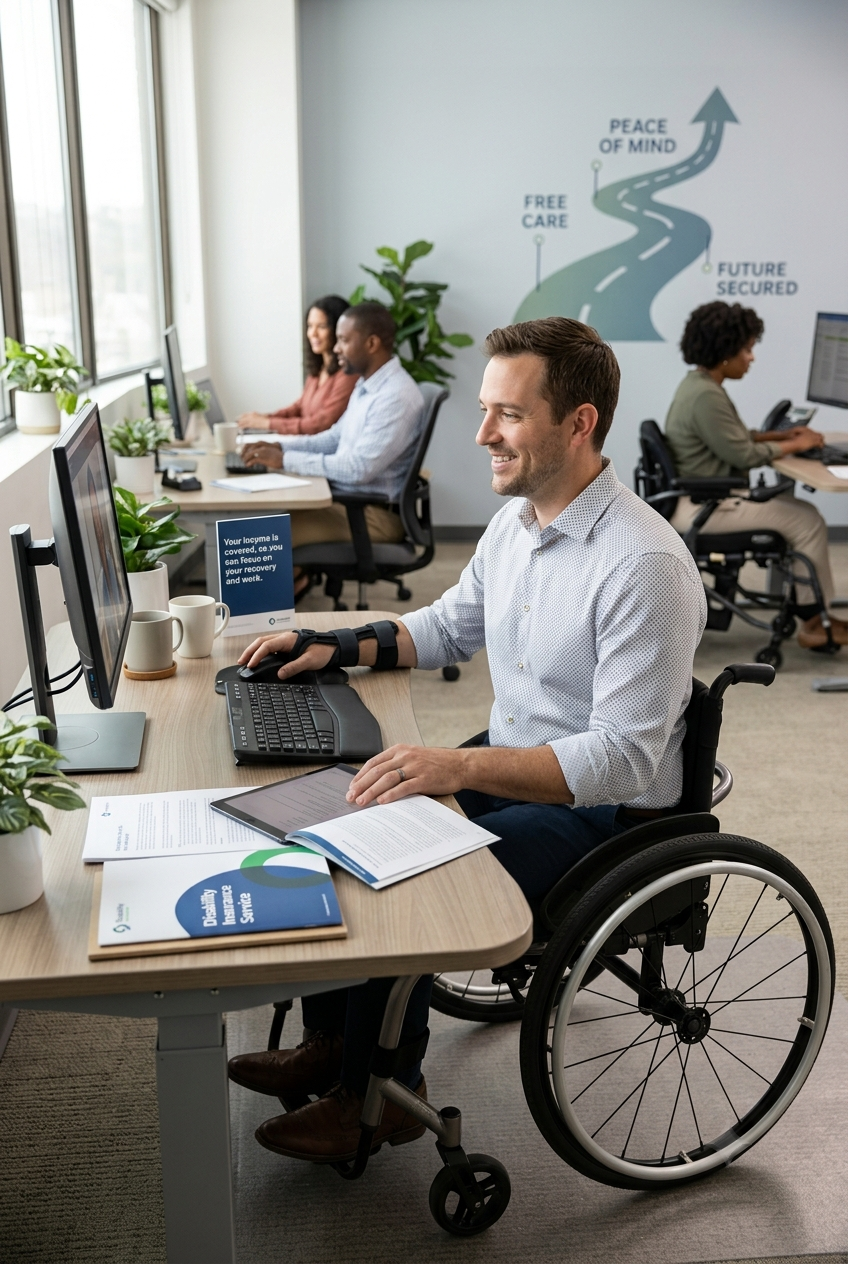
Disability insurance helps replace income if illness or injury prevents you from working. For many clients, the ability to earn an income is one of their most valuable financial assets.
Best For
Self-employed professionals
Contractors
Business owners
Health care professionals
Families relying on one or two incomes
Employees with limited workplace benefits
Additional Plan Details
Common Uses
• Replace monthly income
• Pay mortgage or rent
• Cover household bills
• Protect retirement savings from early withdrawals
• Protect business overhead expenses
• Maintain financial stability during recovery
Quick Questions Clients Should Ask
• How much of my income is protected today?
• Does my workplace plan cover enough?
• What happens if I can work part-time but not full-time?
• How long would benefits last?
• Does the policy protect my specific occupation?
• Should I also consider business overhead coverage?
Key Features to Review
• Monthly benefit amount
• Waiting period
• Benefit period
• Own occupation definition
• Any occupation definition
• Partial or residual disability benefit
• Cost-of-living adjustment
• Non-cancellable or guaranteed renewable features
Common Mistakes
• Assuming government benefits are enough
• Not knowing the definition of disability inside the policy
• Underestimating how long a disability can last
• Not protecting business expenses
• Waiting until health changes affect eligibility
Protect Your Business. Plan for the Future.
Schedule an income protection review to understand how disability insurance may help protect your paycheque, family, and business.